A savings group share-out or a first loan is often the capital for a first business. What happens next follows a fairly predictable pattern, and the failures are predictable too.
Sell something people already buy
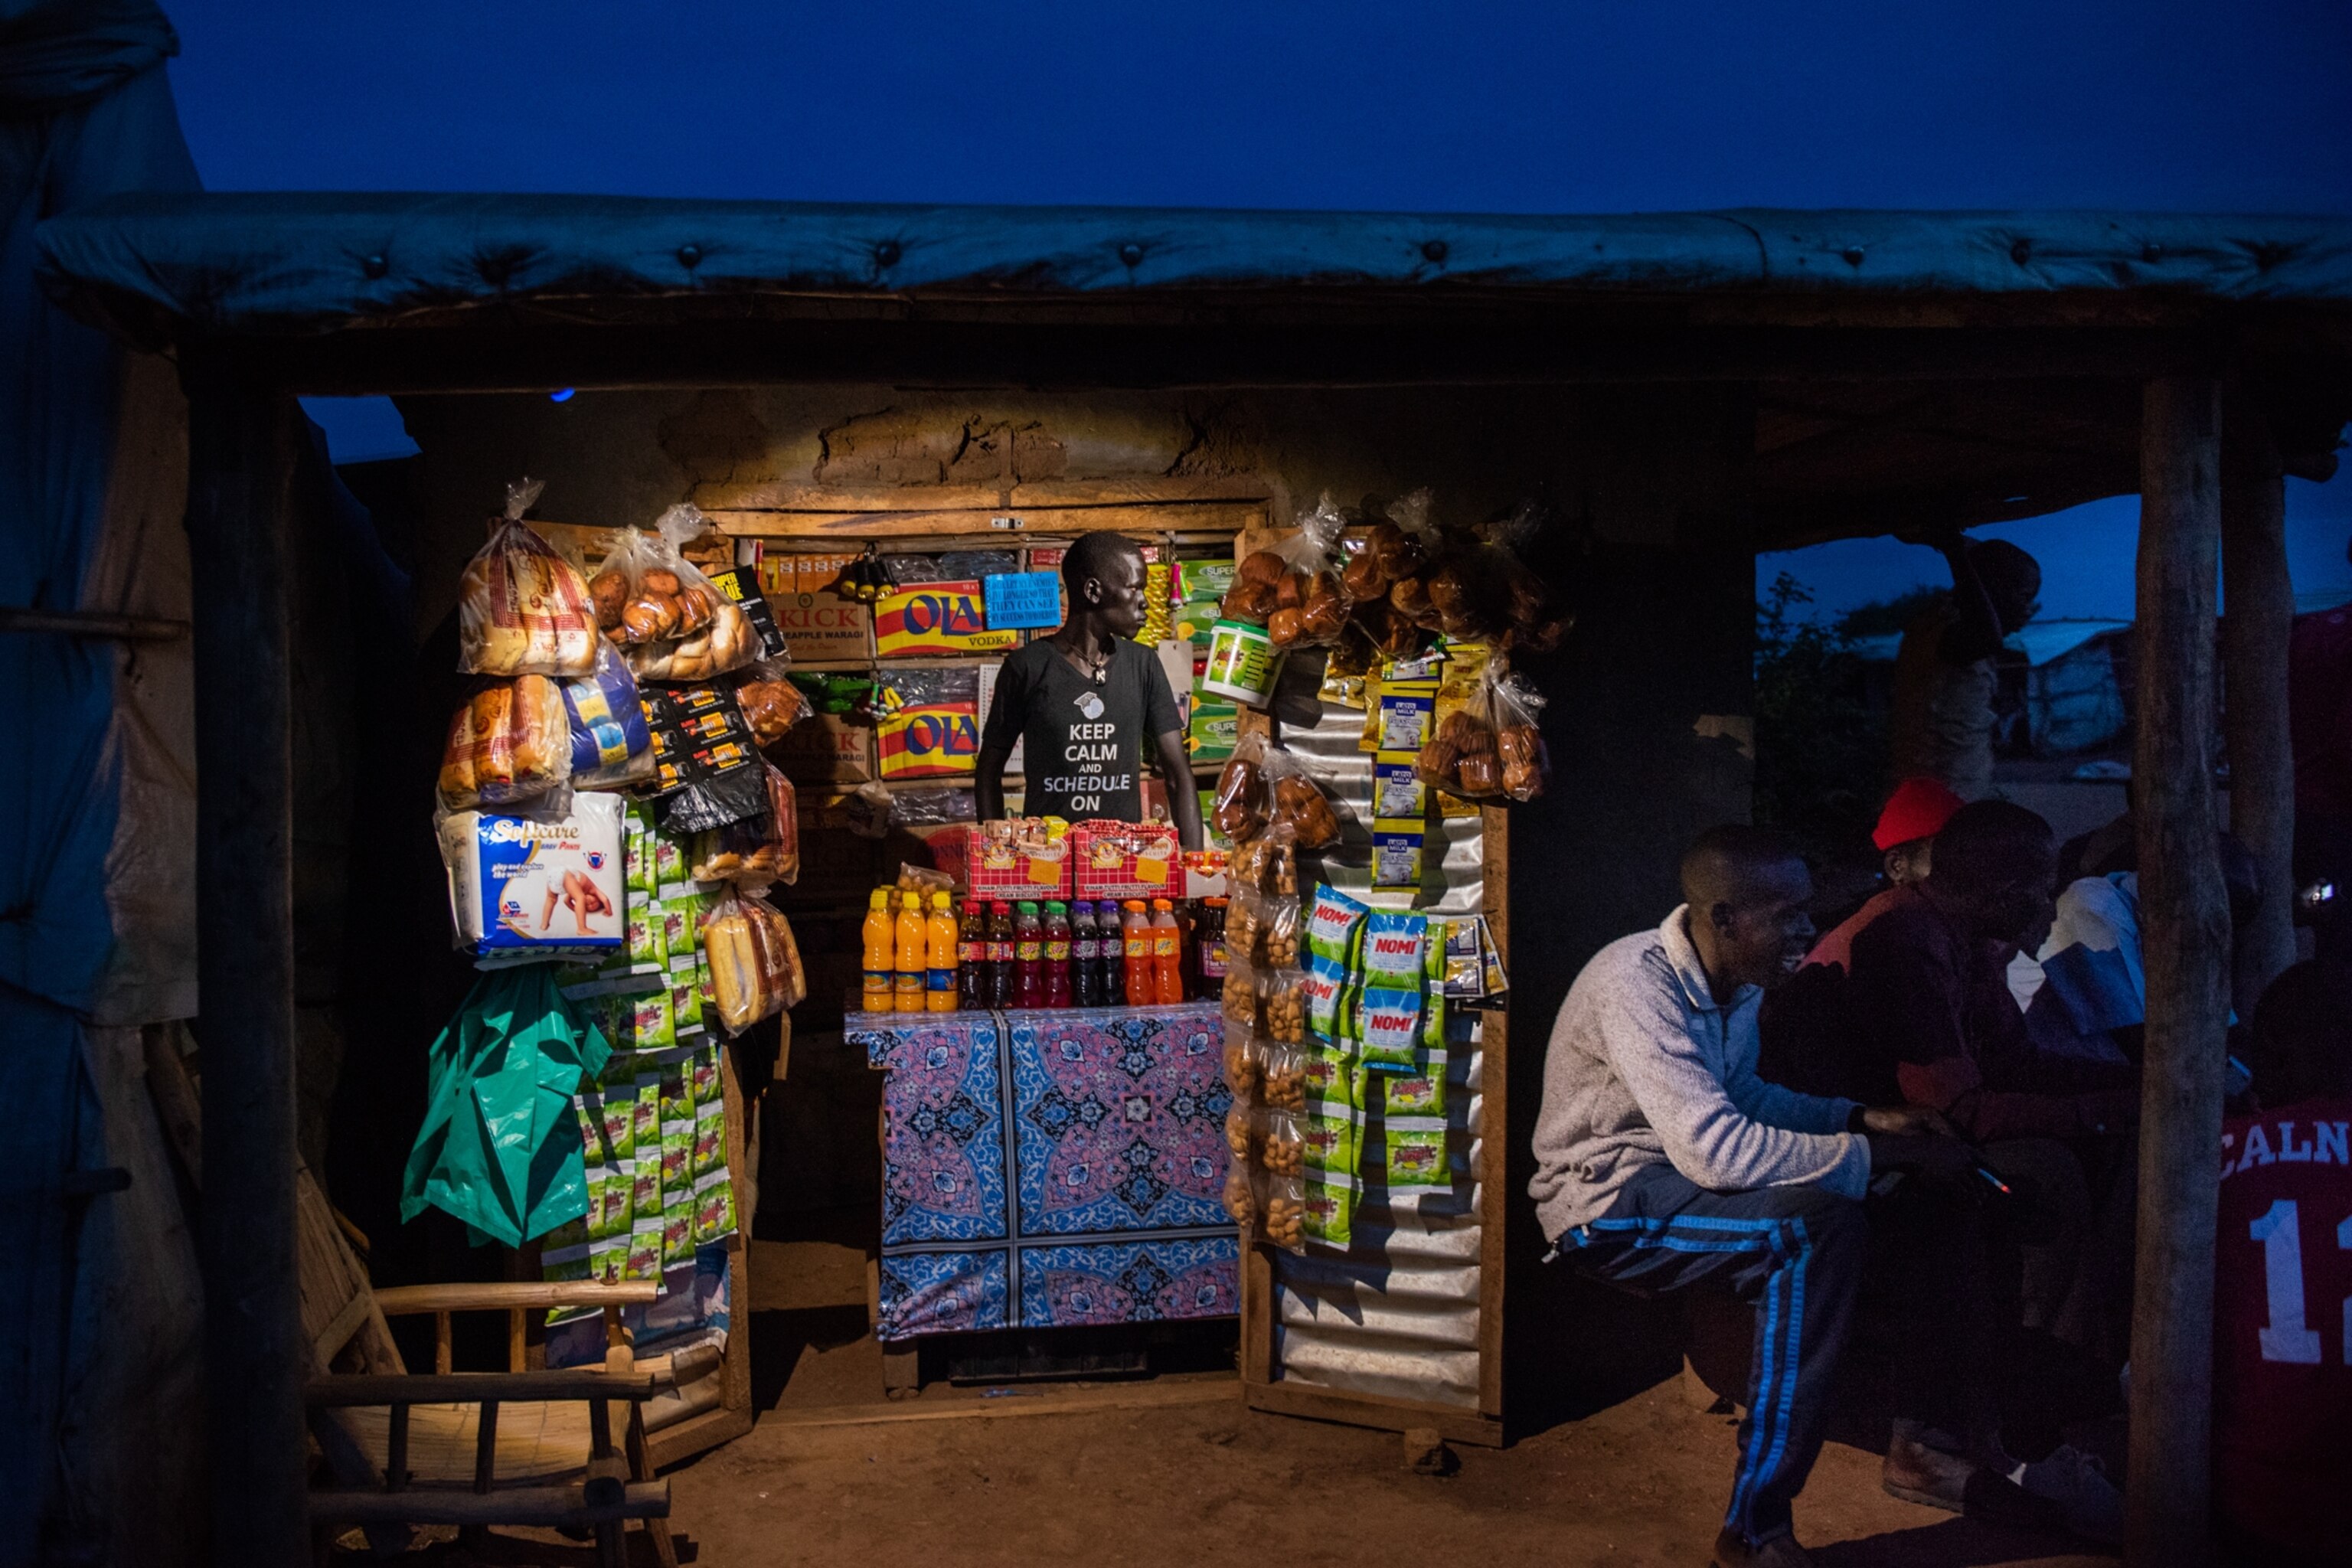
The safest first business sells a product with existing weekly demand in your own community: soap, salt, sugar, cooking oil, charcoal, airtime, tomatoes, second-hand clothes. You are not creating demand, only capturing it closer to where people live.
Businesses that require you to persuade people to want something new need more capital and more time than a first venture can carry.
Know your margin per unit before you start
This is the number most new traders cannot state, and it decides everything.
Worked example. You buy a case of 24 bars of soap for 48,000 shillings, so 2,000 per bar. You sell at 2,500. Your margin is 500 per bar, or 12,000 per case.
Now subtract what it costs to be in business: transport to buy stock, market dues, any rent, and the value of your own time. If those come to 6,000 a week and you sell one case a week, your actual profit is 6,000 a week, not 12,000. Many traders count the first figure and wonder where the money went.
Work out your break-even
Divide your weekly fixed costs by your margin per unit. At 6,000 of weekly costs and 500 per bar, you must sell 12 bars a week simply to cover costs. Everything beyond 12 is profit. Now you have a target you can check daily.
Test before you borrow
Run the business for a month at the smallest possible scale, using your own money. Not to make a profit, to learn:
- How many units actually sell in a week, as opposed to how many you hoped.
- Which days are busy.
- What customers ask for that you do not stock.
- Whether your supplier is reliable.
A month of small trading tells you more than any plan. Borrow after that month, sized to what you learned.
Keep business money separate from household money
This is the single most common reason small businesses fail here. Stock money gets spent on a household need, the next restock is short, the stock shrinks, and the business quietly dies over about four months.
Fix it with two rules: keep business cash in a physically separate place, and pay yourself a fixed, modest amount on a fixed day. That payment is the household's income. Everything else stays in the business.
The credit problem
Customers will ask to buy on credit, and refusing neighbours is hard. Rules that work:
- A fixed ceiling on total credit outstanding, perhaps a tenth of your stock value.
- Write every credit sale down, with the name and date, in front of the customer.
- No new credit to anyone who has not cleared the last.
- Never give credit on the day you need to restock.
When should I take a second loan?
When the first loan is fully repaid, the business has been running at least three months, you know your weekly sales figure from records rather than memory, and the new capital has a specific purpose you can name. "To grow the business" is not a purpose. "To buy stock in bulk at the wholesale price, saving 200 shillings per bar" is.
Grow by stock depth first
Before adding new product lines or a second location, deepen what already sells. Running out of your best-selling item is the most expensive mistake a small trader makes, because the customer goes elsewhere and often stays there.