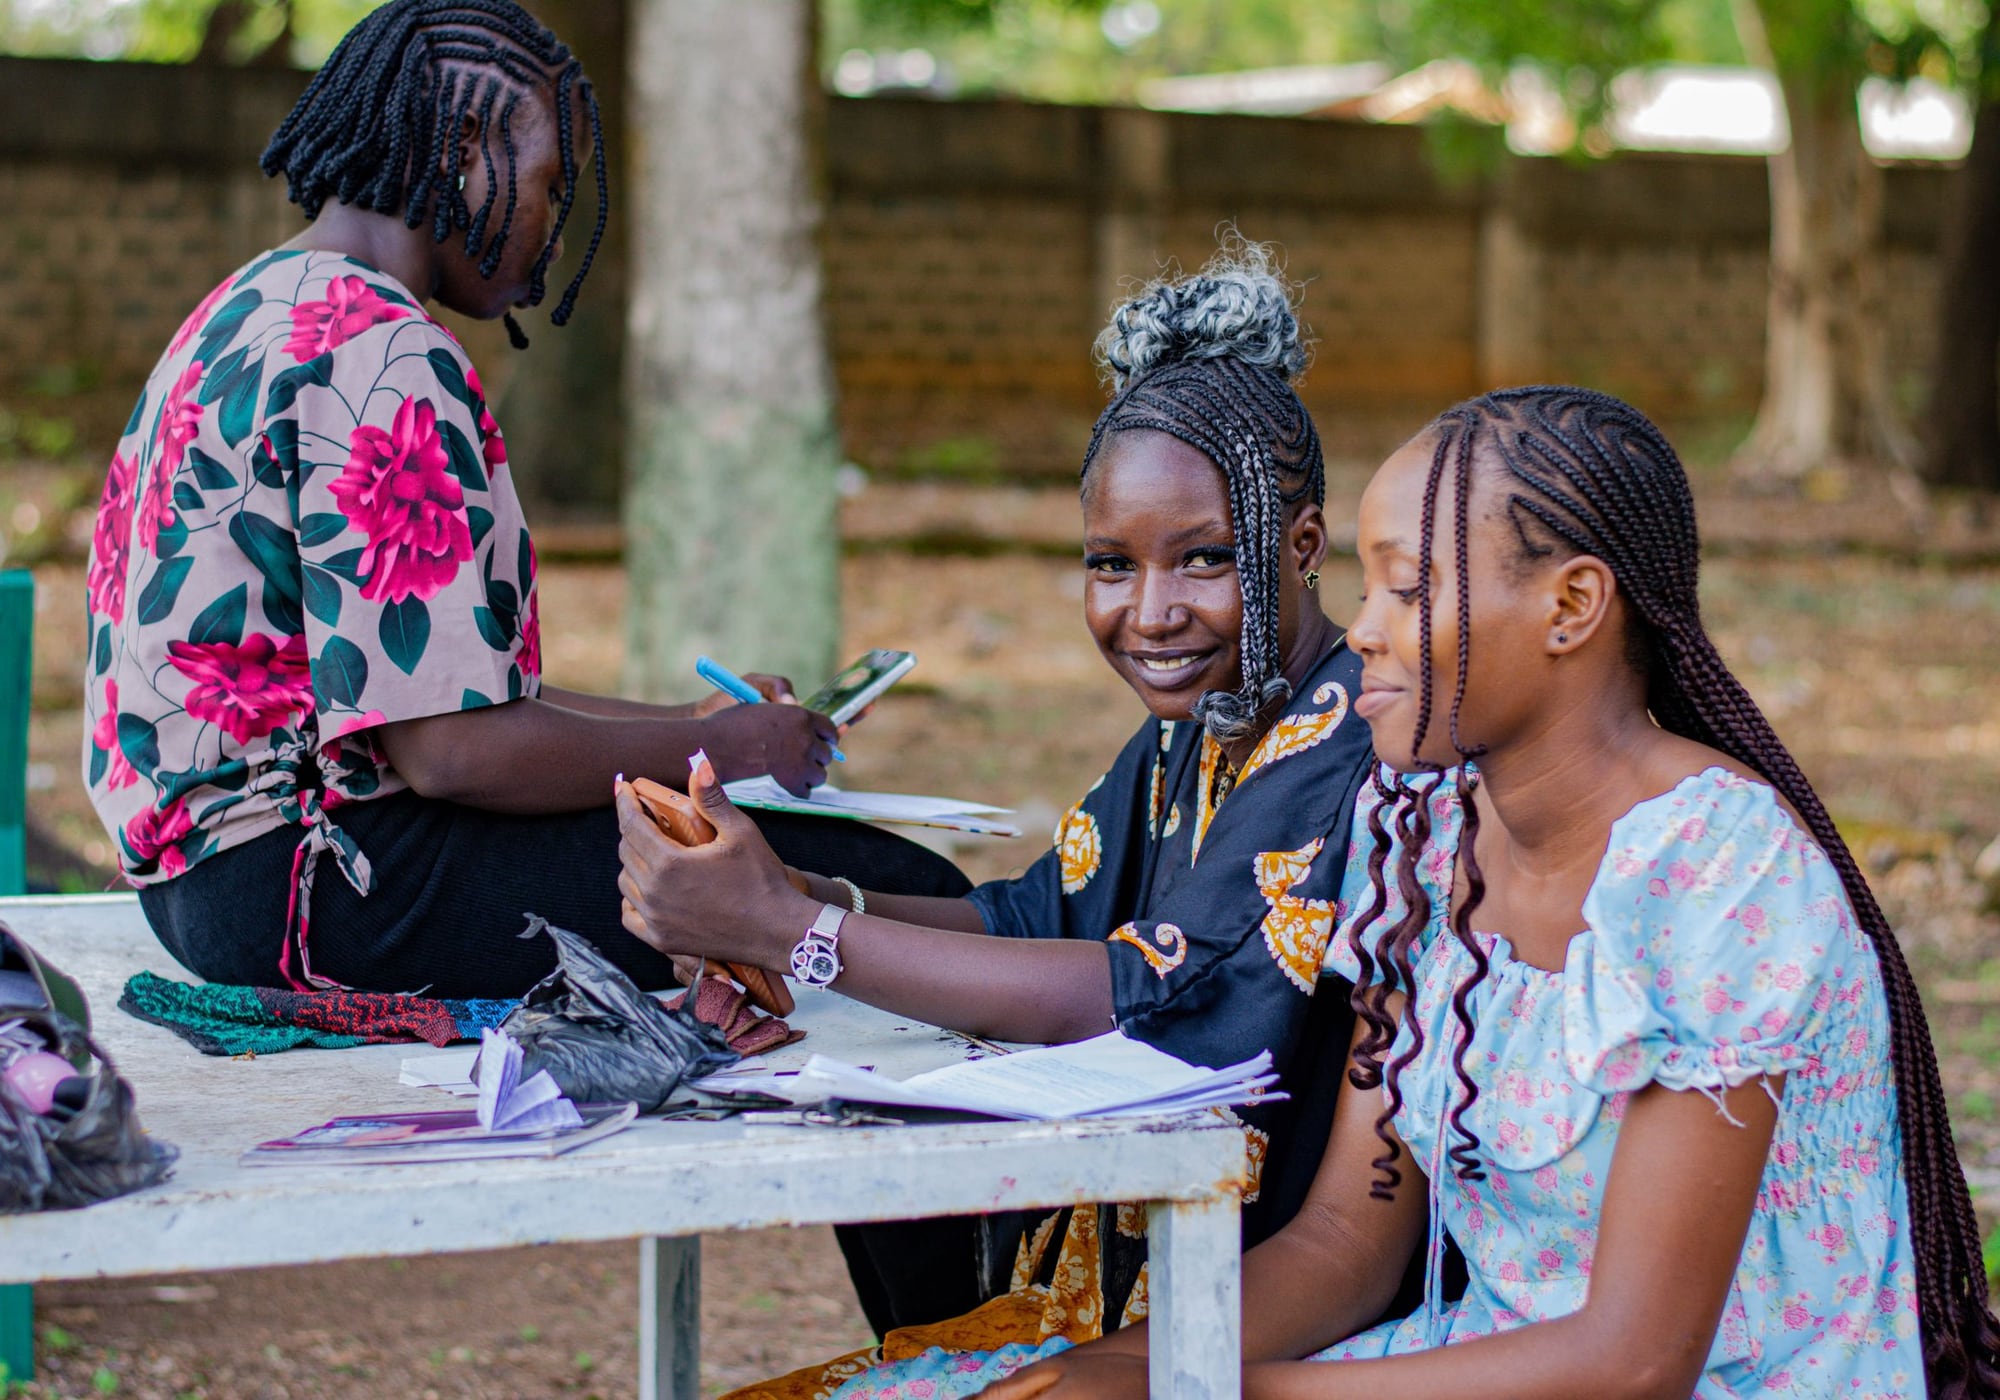
Village savings and loan associations are the most widely used savings method in rural Uganda, and the reason is simple: they work without a bank, without literacy requirements, and without anyone from outside holding the money.
How a VSLA actually works
Fifteen to twenty five people, usually neighbours, agree to meet weekly. At each meeting every member buys between one and five shares. A share has a fixed price the group sets itself. The money goes into a lockable cash box.
Once the fund has built up, members borrow from it. Loans are typically repaid over one to three months with a service charge the group sets, commonly around 5 to 10 per cent per month. That charge is not a bank's profit. It stays in the fund and comes back to the members.
After an agreed cycle, usually nine to twelve months, the group shares out everything: each member's savings plus their proportional share of the interest earned. Then a new cycle begins.
The social fund
Most groups also run a small separate social fund, with a fixed contribution from every member each week. It pays out as a grant, not a loan, for emergencies: a funeral, a serious illness, a fire. It is what stops a family selling their goat the week something goes wrong.
Keep the social fund physically and administratively separate from the loan fund. Groups that mix them lose track of both.
Why the share-out matters
The annual share-out is what distinguishes a VSLA from a bank account, and it is why the model spreads on its own. Members see a visible lump sum at a predictable time. Many time their cycle to end just before school fees are due, or before the planting season when seed and inputs must be bought.
What does a group need to start?
- Fifteen to twenty five members who already know and trust each other.
- A lockable box with three different padlocks, and three different keyholders.
- A written constitution the group agrees before the first contribution.
- Elected officers: chairperson, secretary, treasurer or box keeper, and two money counters.
- A record system, whether passbooks or a ledger.
- A fixed meeting day, time and place.
What it does not need is external capital. Groups seeded with donor money almost always perform worse, because members treat it as someone else's money rather than their own.
The rules that prevent most failures
- Count the money in front of everyone, every meeting. Opening and closing balances read aloud.
- The box never leaves the meeting with one person. Three locks, three keyholders, and the box stored with a fourth member who has no key.
- No loan larger than three times a member's own savings. This caps the damage from any single default.
- Write every transaction down at the moment it happens, not afterwards from memory.
- Officers are elected each cycle, so no one becomes permanent.
How long before a group is useful?
Realistically, the fund is too small to lend from for the first six to eight weeks. This is the point at which weak groups collapse, because members are contributing and getting nothing back. Say so at the start. A group that expects the slow beginning survives it.
Is the interest charge permissible?
This question comes up in Muslim communities and deserves a straight answer rather than avoidance. Many scholars regard a fixed charge on a cash loan as riba regardless of who receives it. Alternatives that groups in Uganda use include a flat administrative fee that reflects actual running costs, or a profit-sharing arrangement where the group invests together and shares the outcome rather than lending at a fixed return.
Where your community wants the savings discipline without the interest structure, discuss the model with a scholar before the first meeting, not after the first cycle. The savings, share-out and social fund mechanics work without the interest charge; the fund simply grows more slowly.
Where groups go wrong
The commonest failures, in order: officers who are related to each other, records kept in one person's head, loans given to members who are already behind on repayment, and cycles that run past twelve months so that members lose sight of the share-out. All four are avoidable with rules written at the start.
IDPN runs financial skills training with women's groups in West Nile. If your group is forming and wants someone to sit through the first meetings, contact the office.